
A finance plan should make a driveway or patio project manageable, not leave you unsure about repayments. Driveway finance options in the West Midlands can include interest-free credit, 0% APR offers and fixed-rate borrowing. Missed payments can cause financial difficulties and negatively affect your credit score, so it’s important to understand the agreement before committing.
It’s reasonable to wonder whether applying could affect your credit score, as well as how deposits and repayment terms work. This guide explains what to look for in a finance assessment, how 0% APR and deposits may fit into an agreement, and how driveway finance works across the UK.
You’ll also see why getting a clear project quote first helps you understand how much you may need to borrow and what to consider when financing driveway or patio work. The aim is simple: understand the options and choose an approach that fits your budget.
Key Takeaways
- Work out what repayment you can manage and understand how the lender assesses an application before deciding whether to proceed.
- Compare the terms of any 0% APR offer and factor in a possible deposit when planning how much to borrow.
- Understand the role of the regulated lender: driveway installers generally introduce customers to a lender rather than lend money themselves.
- Get a clear project quote before applying, then use the lender’s final agreement details to understand the repayments and total amount payable.
How Do Customers Evaluate Driveway Finance?
Start with the monthly repayment, total payable and agreement term, not just the advertised rate. When comparing driveway finance options in the West Midlands, check that the repayments fit your budget throughout the term.
Assessing affordability and repayments
Work out what you can comfortably repay each month after essential household costs. The amount borrowed and repayment period determine your monthly payments. With interest-free credit, the amount borrowed is divided across the agreement term, with no interest or fees payable. Flexible finance may allow additional payments without penalty, potentially reducing the term and interest payable. Leave enough room in your budget for every scheduled repayment.
Representative repayment examples
These examples show why the deposit, APR and term matter: compare the full amount payable, not just one monthly figure. Your repayment depends on the agreement details and amount borrowed.
Comparing finance with other borrowing
A 0% interest driveway finance deal means repaying only the amount borrowed, subject to lender approval. Personal loans and credit cards have their own rates and terms, so compare each option’s total repayment, fees and payment schedule before taking credit. An application’s effect on your credit score depends on the lender’s assessment process; missed payments can cause financial difficulties and negatively affect your score.
Understanding costs, rules and risks
Before signing, review the APR, any fees, deposit, repayment term and total payable in the written agreement. Check whether the borrowing is secured and what that means for you; charges for missed payments depend on the agreement. In England, planning permission and surface-water drainage requirements depend on the project and site, so don’t assume a permeable surface alone settles the question. Compare written quotes by scope and materials, and consider the installer’s credentials and insurance alongside the finance terms.
0% APR finance and deposit requirements
A 0% APR offer can reduce borrowing costs, but approval and deposit requirements affect how much you finance. Check the offer’s duration and cash contribution before choosing a repayment plan.
Understanding 0% APR finance
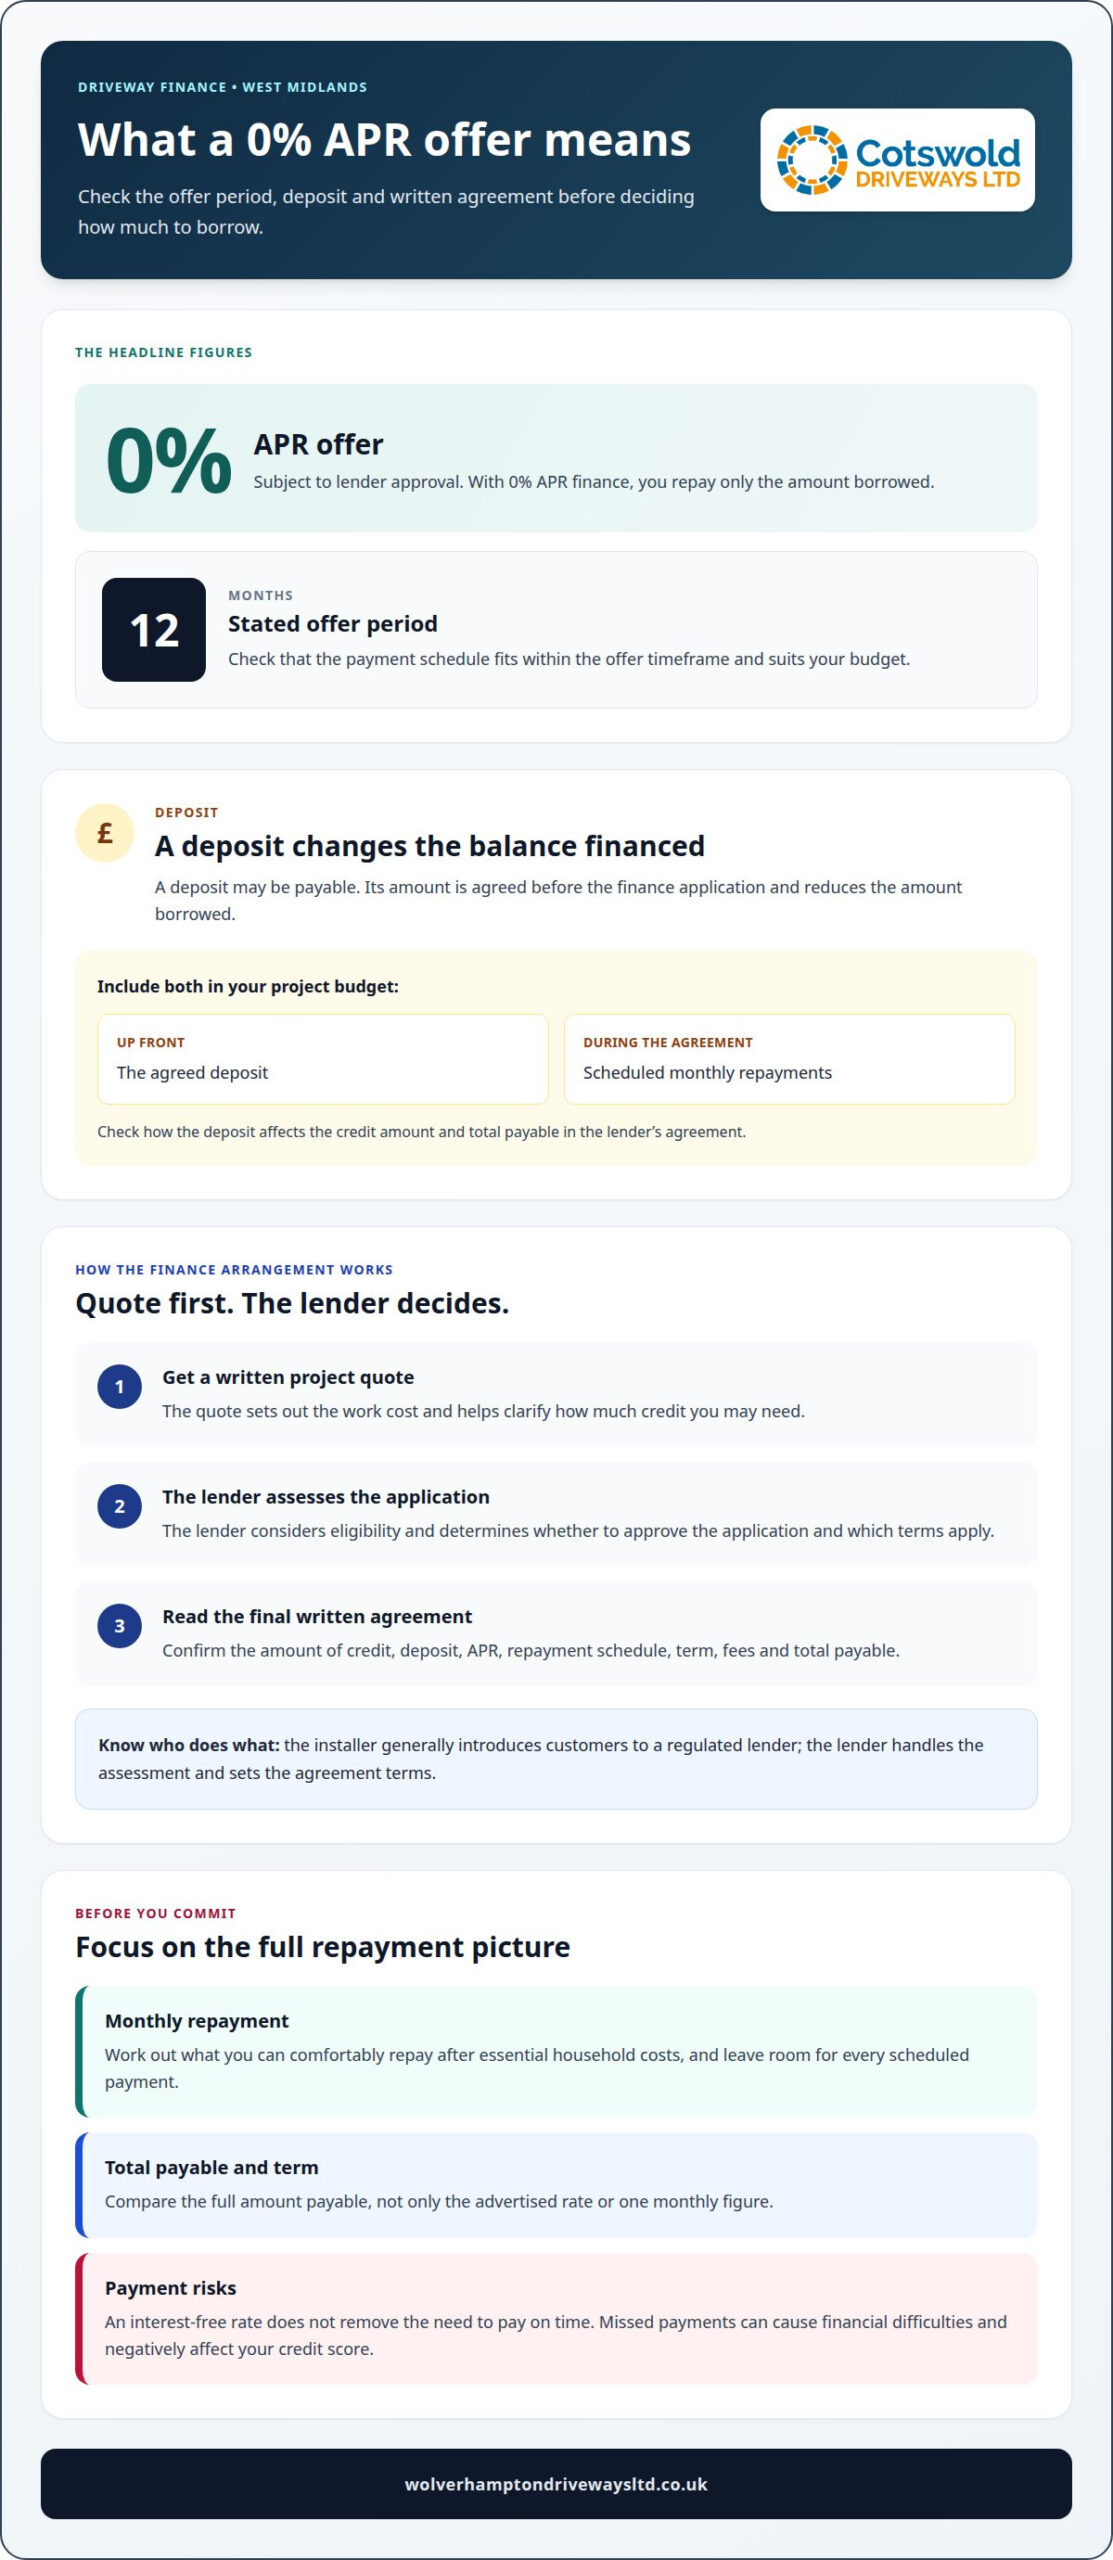
With 0% APR finance, you repay only the amount borrowed, subject to lender approval. The stated offer period is 12 months, so check how repayments fit within that timeframe. Confirm the amount financed, payment schedule and agreement conditions before applying. An interest-free rate doesn’t remove the need to make each payment on time.
Some people prefer to spread a project’s cost, while others may prefer to pay upfront. The right choice depends on your budget and the written terms, not just the label. Finance is arranged through lenders, and an installer generally introduces customers to a regulated lender rather than lending directly. A credit broker can introduce borrowers to a lender; the agreement sets out the lender’s terms. Treat finance as a borrowing decision, not simply a way to make a sale.
A calculator provides an estimate only; the exact details are set out during the application process.
Checking deposit requirements
A deposit may be payable, and its amount is agreed before you begin the finance application. It reduces the balance financed, so include it in your project budget alongside the monthly repayment. Check how the deposit affects the credit amount and total payable shown in the agreement.
This example shows how a deposit changes the amount borrowed; it doesn’t establish the deposit for every agreement. The lender’s approval and the agreed offer determine the actual arrangement.
Get a written project quote first, so the amount you may need to borrow is clear. You can request a driveway quote before considering the finance application.
Is finance available across the UK?
In the UK, driveway finance is arranged through lenders, with the application and assessment handled under the lender’s process. The installer generally introduces you to a lender rather than lending money directly.
Applying for finance
Start with a written quote for the paving work. It sets out the project cost, helping you understand how much credit you may need before applying. Then complete the lender’s application or speak with a finance provider’s specialist. The lender considers your application and sets out its decision and agreement terms.
Provide accurate information in the application and review the lender’s terms carefully. The lender pays the driveway business after approval and once any required conditions are met. A calculator can provide an estimate, but the application process supplies the exact finance details. This helps distinguish an early repayment estimate from the final agreement.
Eligibility and lender arrangements
The lender assesses your eligibility; the driveway installer does not decide whether you qualify. The lender’s assessment determines whether it approves the application and which agreement terms apply. Before accepting, read the terms, including the amount of credit and repayment schedule. Every application is subject to the lender’s decision.
Consumer credit activity in the UK is regulated by the Financial Conduct Authority. Driveway businesses generally introduce customers to a regulated lender rather than lending themselves. A business that introduces finance may need authorisation or may work with an authorised provider that manages the regulated elements. The introducer and lender therefore have distinct roles.
For a West Midlands project, the practical steps are the same as elsewhere in the UK: obtain a quote, apply through the finance route and read the lender’s agreement. The lender usually pays the installer directly after approval and once any required conditions are met. The paving work itself does not determine approval; the lender’s assessment and agreement do.
Finance options for driveway and patio projects
Finance can help spread the cost of a driveway or patio, but your agreement is with a lender, not necessarily the installer. The key distinction is whether a business introduces you to a lender or lends directly. Driveway installers generally act as introducers, while a regulated lender assesses the application and sets the agreement terms.
There is no single payment plan shared by every West Midlands driveway company. Businesses that arrange finance usually connect customers with a lender or finance broker; the lender’s approval, offer and conditions determine the available borrowing. Ask how the process works and who makes the lending decision. A finance specialist can explain the application route and repayment schedule, but the written agreement sets out your commitment.
Plan the project before applying. First, obtain a written quote that separates the work included, such as driveway or patio installation, from any other items. Then decide how much you intend to pay upfront and how much credit you would need. A lender generally pays the driveway business directly after approving the agreement and confirming any required conditions have been met.
A finance calculator provides an estimate, not the final offer. The exact details are supplied during the application process. Use your written quote and the lender’s final agreement to understand the amount financed and payments due.
Before taking credit, compare the total payable, interest, deposit and repayment period. Consider whether each payment remains manageable for the full term, including if your household budget changes. This applies to patio projects as well as driveways: the amount borrowed depends on the quoted work and your chosen upfront contribution. To plan the project amount, request a driveway or patio quote before applying.
Wolverhampton Driveways: Driveway Cleaning & Repairs
Wolverhampton Driveways Ltd can help you plan the driveway work behind your finance decision, whether your existing surface needs attention or you’re considering a new finish. Driveway Cleaning & Repairs suits driveways that need cleaning or repair, while Tarmac Driveways, Block Paving and Resin Bound Driveways offer options for a new installation. A clear project scope helps you understand the work you’re considering before deciding whether to borrow. The lender sets the finance terms, so base any application on the agreed work and your budget. If you’re planning a driveway project in Wolverhampton, Telford, Cannock, Dudley or the wider West Midlands, contact Wolverhampton Driveways Ltd to discuss the work you have in mind.
Take the Next Step Towards Your Driveway Project
Before deciding whether to borrow, clarify what you want from your outdoor space. A well-defined project gives you a practical starting point for discussing the work and assessing how it fits your household budget. If you’re weighing driveway finance options in the West Midlands, shape the project first, then compare the borrowing with the lender’s terms.
Wolverhampton Driveways Ltd can help bring your project into focus with Tarmac Driveways, Block Paving or Resin Bound Driveways. Consider the finish that suits your home and how you use the space, then discuss the work you have in mind. There’s no need to rush a finance decision. A clear plan helps you assess what you want to achieve before considering the lender’s terms.
Ready to talk through your driveway project? Contact Wolverhampton Driveways Ltd to discuss the next step and start planning with confidence.
Frequently Asked Questions
Does applying affect my credit score?
It can, depending on the lender’s application process and the type of credit check used. The lender assesses your application, while missed payments can negatively affect your credit score. Before applying, read the lender’s explanation of its checks and consider whether you can maintain repayments throughout the agreement. If comparing offers, understand how each lender handles its assessment before submitting applications.
How do I Apply for Finance?
Start by getting a written quote, then follow the finance provider’s application process. You may complete an application form or speak with a specialist. Have the project amount and any deposit in mind, and read the lender’s offer carefully before accepting. The lender must approve the application and any required conditions must be met before it pays the business, so don’t treat an estimate as a confirmed agreement.
Is 0% finance really interest free?
Yes, a 0% APR agreement means repaying only the amount borrowed, with no interest, subject to lender approval and the agreement terms. Check that the written offer actually shows 0% APR and review its repayment period, deposit requirements and fees. For example, an interest-free offer over 12 months requires you to understand how the scheduled payments fit your budget.
What Does It Mean to Offer Driveway Finance?
Usually, it means the driveway business introduces customers to a regulated lender rather than lending its own money. The lender assesses applications, decides whether to approve credit and provides the agreement. Consumer credit activity in the UK is regulated by the Financial Conduct Authority. The business may act as an introducer, while an authorised provider manages regulated elements of the finance process.
What driveway finance options are available in the West Midlands?
Driveway finance options in the West Midlands may include interest-free credit, 0% APR offers and fixed-rate borrowing, depending on the lender and its approval. The finance provider sets the agreement, rather than a particular surface or location. Whether your project is in Wolverhampton, Telford, Cannock or Dudley, get a quote first so you can assess the amount you may need to finance.
What credit checks and eligibility requirements apply to driveway finance in the UK?
The lender assesses your application and decides whether to approve the borrowing; eligibility requirements depend on its criteria. The assessment considers the amount requested and your ability to keep up with repayments. A deposit may also affect how much credit you apply for. Read the lender’s explanation of its checks and agreement before proceeding, as the finance provider sets the requirements.